5859 W Maple Road, West Bloomfield, MI  ·  Tours daily, 9am–5pm
Comfort Cove Senior Living · West Bloomfield(248) 538-5283
← The Cove Journal

A Practical Guide to Retirement Budgeting Choices

·6 min readA Practical Guide to Retirement Budgeting Choices
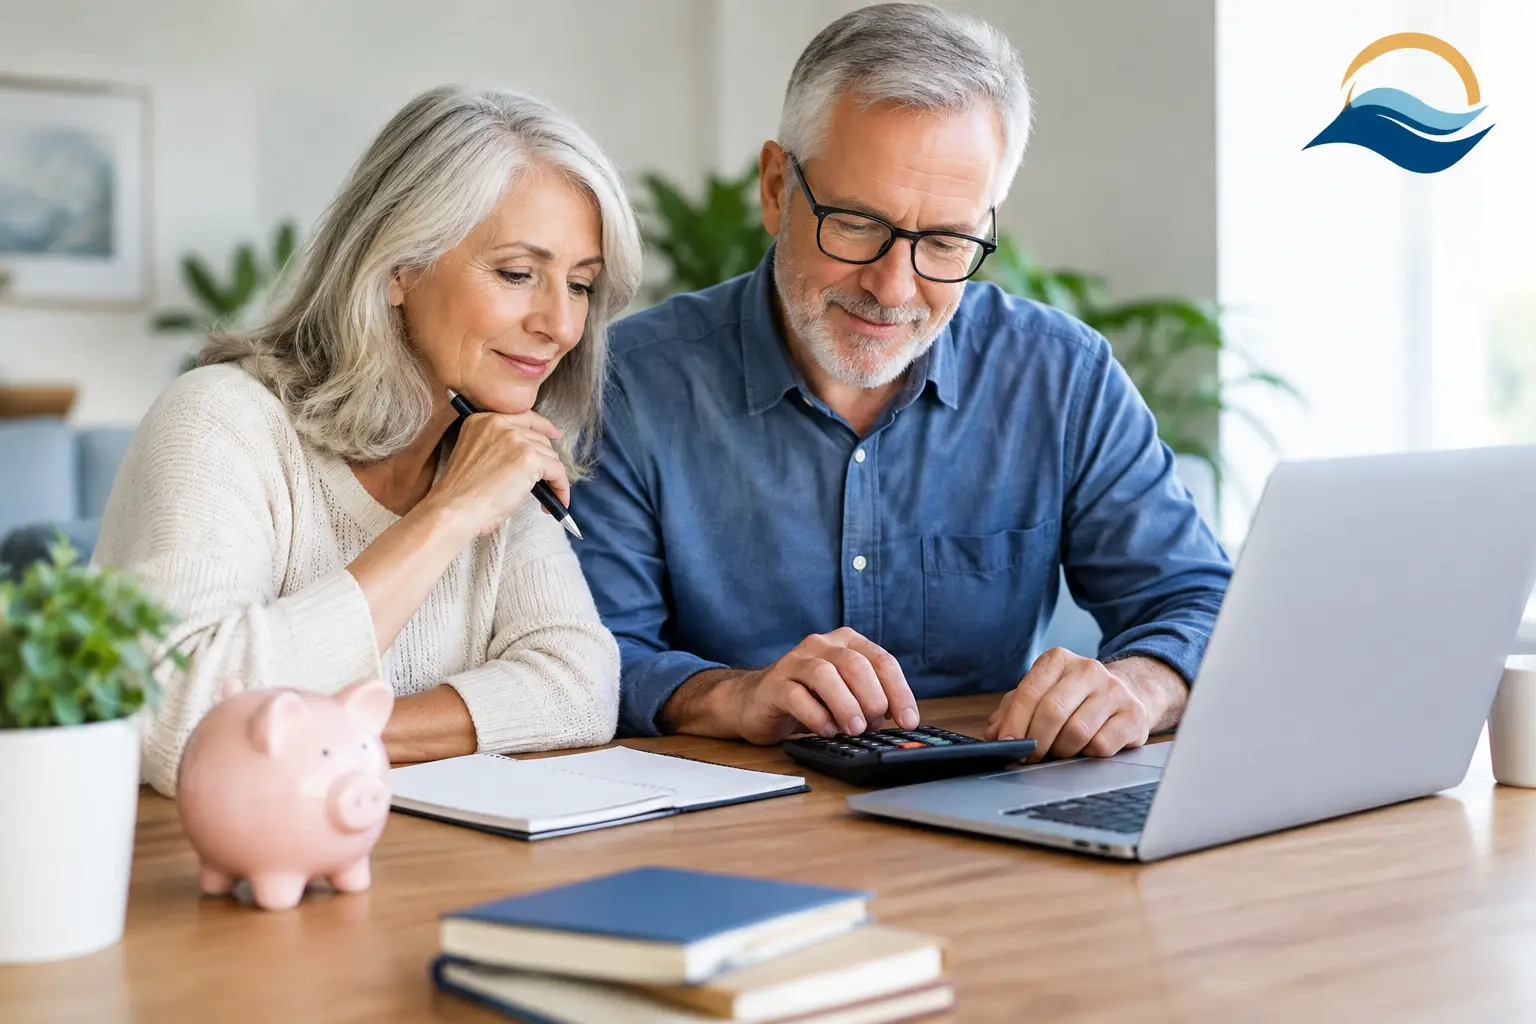
The monthly cost of retirement is rarely just the number on a mortgage statement or rent check. A beloved home may also require repairs, property taxes, groceries, transportation, yard work, utilities, and help when a task becomes harder to manage alone. A thoughtful guide to retirement budgeting choices begins by looking at the whole picture: what supports comfort, independence, connection, and peace of mind now and in the years ahead.

For older adults and the families who love them, this is not simply a financial exercise. It is a chance to shape a next chapter with room for joy, security, and the kind of daily support that makes life feel lighter.

Start With the Life You Want to Live

Before comparing costs, talk about priorities. Some retirees want to stay close to longtime neighbors. Others are ready to exchange home maintenance for chef-prepared meals, meaningful activities, and a welcoming community of peers. Many families are seeking reassurance that a loved one can remain independent while having support nearby if needs change.

These preferences should guide the budget, not come after it. A lower monthly expense may not be the better value if it leaves a person isolated, responsible for a demanding home, or without a plan for changing health needs. On the other hand, a senior living community should feel like a genuine fit for a resident's routines, personality, and financial comfort.

Consider what an ideal week looks like. Does it include driving to appointments, preparing every meal, handling household repairs, and coordinating social plans? Or would it feel more fulfilling to enjoy an engaging calendar of events, restaurant-style dining, housekeeping-style convenience, and time for favorite hobbies and family visits?

Guide to Retirement Budgeting Choices: Look Beyond Housing

A useful retirement budget separates predictable living costs from expenses that arrive unexpectedly. This approach helps families compare aging at home with independent senior living fairly, rather than placing a single community rate beside only a mortgage payment.

Add up the true cost of remaining at home

Start with regular household expenses: mortgage or rent, property taxes, homeowners insurance, utilities, internet, groceries, home and auto maintenance, and transportation. Then include services that may become more valuable over time, such as cleaning help, lawn care, snow removal, meal delivery, rides to appointments, and home modifications.

In Michigan, seasonal upkeep deserves special attention. Snow removal, furnace maintenance, roof repairs, and transportation during winter weather can affect both a household budget and a family's sense of security. Even a home that is fully paid off has ongoing costs, and major repairs can be difficult to predict.

It also helps to consider the hidden cost of coordination. When an adult child manages prescriptions, appointments, repairs, groceries, and check-ins from across Oakland County or from another state, the financial picture is only part of the story. Time, worry, and caregiver strain matter, too.

Understand what a community monthly fee includes

In a premier independent living setting, a monthly rate often combines many expenses that are separate at home. Depending on the residence and selected services, that may include an apartment, dining, utilities, maintenance, programming, community spaces, security, and access to a team that knows residents personally.

Ask for a clear explanation of what is included and what may cost extra. Families should understand apartment options, dining arrangements, transportation availability, laundry and housekeeping services, personal support, and the pricing for care if it is needed later. Transparent conversations make it easier to budget with confidence.

The value is not that every service will be used every day. It is that support, social connection, and hospitality are close at hand when they add meaning or ease. For many residents, that availability is part of what makes a community feel like home.

Build a Budget Around Reliable Income

Once living expenses are clear, identify dependable monthly income. Social Security, pensions, annuities, required retirement account distributions, investment income, and rental income may all contribute. Families should distinguish between guaranteed income and assets that can fluctuate, especially when relying on investments to cover a monthly shortfall.

A practical starting point is to total income after taxes and then compare it with anticipated monthly expenses. If a gap exists, consider how savings, retirement accounts, proceeds from a home sale, or long-term care insurance might responsibly support that gap. A financial advisor or elder law attorney can offer personalized guidance on tax questions, estate planning, and the timing of major decisions.

Avoid assuming that every asset must remain untouched forever. Retirement savings were created to support retirement. The more meaningful question is whether spending is sustainable and whether it helps create a safer, more satisfying quality of life.

Plan for Care Before a Crisis Requires It

Care needs can change gradually or suddenly. A resident may be fully independent today but eventually need help with medication reminders, bathing, mobility, or coordination with hospice services. A complete retirement budget includes room for those possibilities without treating them as a failure of independence.

Communities that offer customizable support can provide valuable continuity. Rather than forcing a move at the first sign of changing needs, they may help residents age gracefully in place with services tailored to the individual. This can reduce disruption and allow relationships with neighbors, team members, and familiar surroundings to continue.

Still, families should ask direct questions. What kinds of assistance are available? How are needs assessed? Can support increase over time? Is respite available after a hospital stay or when a caregiver needs a break? What happens if care needs exceed what the community can provide? Honest answers are a sign of compassionate, responsible service.

Leave Room for the Good Parts of Retirement

A budget made entirely of necessities can unintentionally make retirement feel smaller. Set aside funds for birthdays, gifts, outings, worship, salon visits, travel, hobbies, and meals with family. These are not frivolous extras. They are part of identity, connection, and the pleasure of having time to enjoy life.

Senior living can make room for these moments by reducing the burden of routine tasks. When grocery shopping, cooking, repairs, and cleaning no longer consume so much energy, residents may find more opportunity to participate in programs, make friends, and pursue interests that had been put aside.

For families evaluating Comfort Cove Senior Living, a visit can help turn budget categories into a real-life picture. Touring apartments, asking about dining and activities, and meeting the people who provide daily support can reveal whether the experience matches the investment.

Have the Conversation With Kindness

Money conversations can feel vulnerable, particularly when a parent has always been private or self-reliant. Begin with respect. Ask what matters most to them, what parts of home they treasure, and what would make daily life easier. Listen before offering solutions.

It can help to review options together over more than one conversation. Bring monthly statements, estimates for home expenses, a list of questions, and notes about current support needs. When siblings are involved, share the same information so decisions are based on facts rather than assumptions or uneven responsibilities.

The goal is not to pressure someone into a move or insist on one definition of independence. It is to create choices early enough that the decision can be made thoughtfully, with dignity and family support.

A retirement budget should make space for more than bills. It should make room for a life that feels cared for, connected, and wonderfully one's own. When the numbers support that vision, the next step can feel less like giving something up and more like choosing a home where your story continues.
5859 W Maple Road, West Bloomfield  ·  Tours daily 9–5
Comfort Cove Senior Living · West Bloomfield
← The Cove Journal

A Practical Guide to Retirement Budgeting Choices

·6 min readA Practical Guide to Retirement Budgeting Choices

The monthly cost of retirement is rarely just the number on a mortgage statement or rent check. A beloved home may also require repairs, property taxes, groceries, transportation, yard work, utilities, and help when a task becomes harder to manage alone. A thoughtful guide to retirement budgeting choices begins by looking at the whole picture: what supports comfort, independence, connection, and peace of mind now and in the years ahead.

For older adults and the families who love them, this is not simply a financial exercise. It is a chance to shape a next chapter with room for joy, security, and the kind of daily support that makes life feel lighter.

Start With the Life You Want to Live

Before comparing costs, talk about priorities. Some retirees want to stay close to longtime neighbors. Others are ready to exchange home maintenance for chef-prepared meals, meaningful activities, and a welcoming community of peers. Many families are seeking reassurance that a loved one can remain independent while having support nearby if needs change.

These preferences should guide the budget, not come after it. A lower monthly expense may not be the better value if it leaves a person isolated, responsible for a demanding home, or without a plan for changing health needs. On the other hand, a senior living community should feel like a genuine fit for a resident's routines, personality, and financial comfort.

Consider what an ideal week looks like. Does it include driving to appointments, preparing every meal, handling household repairs, and coordinating social plans? Or would it feel more fulfilling to enjoy an engaging calendar of events, restaurant-style dining, housekeeping-style convenience, and time for favorite hobbies and family visits?

Guide to Retirement Budgeting Choices: Look Beyond Housing

A useful retirement budget separates predictable living costs from expenses that arrive unexpectedly. This approach helps families compare aging at home with independent senior living fairly, rather than placing a single community rate beside only a mortgage payment.

Add up the true cost of remaining at home

Start with regular household expenses: mortgage or rent, property taxes, homeowners insurance, utilities, internet, groceries, home and auto maintenance, and transportation. Then include services that may become more valuable over time, such as cleaning help, lawn care, snow removal, meal delivery, rides to appointments, and home modifications.

In Michigan, seasonal upkeep deserves special attention. Snow removal, furnace maintenance, roof repairs, and transportation during winter weather can affect both a household budget and a family's sense of security. Even a home that is fully paid off has ongoing costs, and major repairs can be difficult to predict.

It also helps to consider the hidden cost of coordination. When an adult child manages prescriptions, appointments, repairs, groceries, and check-ins from across Oakland County or from another state, the financial picture is only part of the story. Time, worry, and caregiver strain matter, too.

Understand what a community monthly fee includes

In a premier independent living setting, a monthly rate often combines many expenses that are separate at home. Depending on the residence and selected services, that may include an apartment, dining, utilities, maintenance, programming, community spaces, security, and access to a team that knows residents personally.

Ask for a clear explanation of what is included and what may cost extra. Families should understand apartment options, dining arrangements, transportation availability, laundry and housekeeping services, personal support, and the pricing for care if it is needed later. Transparent conversations make it easier to budget with confidence.

The value is not that every service will be used every day. It is that support, social connection, and hospitality are close at hand when they add meaning or ease. For many residents, that availability is part of what makes a community feel like home.

Build a Budget Around Reliable Income

Once living expenses are clear, identify dependable monthly income. Social Security, pensions, annuities, required retirement account distributions, investment income, and rental income may all contribute. Families should distinguish between guaranteed income and assets that can fluctuate, especially when relying on investments to cover a monthly shortfall.

A practical starting point is to total income after taxes and then compare it with anticipated monthly expenses. If a gap exists, consider how savings, retirement accounts, proceeds from a home sale, or long-term care insurance might responsibly support that gap. A financial advisor or elder law attorney can offer personalized guidance on tax questions, estate planning, and the timing of major decisions.

Avoid assuming that every asset must remain untouched forever. Retirement savings were created to support retirement. The more meaningful question is whether spending is sustainable and whether it helps create a safer, more satisfying quality of life.

Plan for Care Before a Crisis Requires It

Care needs can change gradually or suddenly. A resident may be fully independent today but eventually need help with medication reminders, bathing, mobility, or coordination with hospice services. A complete retirement budget includes room for those possibilities without treating them as a failure of independence.

Communities that offer customizable support can provide valuable continuity. Rather than forcing a move at the first sign of changing needs, they may help residents age gracefully in place with services tailored to the individual. This can reduce disruption and allow relationships with neighbors, team members, and familiar surroundings to continue.

Still, families should ask direct questions. What kinds of assistance are available? How are needs assessed? Can support increase over time? Is respite available after a hospital stay or when a caregiver needs a break? What happens if care needs exceed what the community can provide? Honest answers are a sign of compassionate, responsible service.

Leave Room for the Good Parts of Retirement

A budget made entirely of necessities can unintentionally make retirement feel smaller. Set aside funds for birthdays, gifts, outings, worship, salon visits, travel, hobbies, and meals with family. These are not frivolous extras. They are part of identity, connection, and the pleasure of having time to enjoy life.

Senior living can make room for these moments by reducing the burden of routine tasks. When grocery shopping, cooking, repairs, and cleaning no longer consume so much energy, residents may find more opportunity to participate in programs, make friends, and pursue interests that had been put aside.

For families evaluating Comfort Cove Senior Living, a visit can help turn budget categories into a real-life picture. Touring apartments, asking about dining and activities, and meeting the people who provide daily support can reveal whether the experience matches the investment.

Have the Conversation With Kindness

Money conversations can feel vulnerable, particularly when a parent has always been private or self-reliant. Begin with respect. Ask what matters most to them, what parts of home they treasure, and what would make daily life easier. Listen before offering solutions.

It can help to review options together over more than one conversation. Bring monthly statements, estimates for home expenses, a list of questions, and notes about current support needs. When siblings are involved, share the same information so decisions are based on facts rather than assumptions or uneven responsibilities.

The goal is not to pressure someone into a move or insist on one definition of independence. It is to create choices early enough that the decision can be made thoughtfully, with dignity and family support.

A retirement budget should make space for more than bills. It should make room for a life that feels cared for, connected, and wonderfully one's own. When the numbers support that vision, the next step can feel less like giving something up and more like choosing a home where your story continues.

Questions a blog post can't answer

Call and talk it through with someone who does this every day. Tours run daily from 9am to 5pm.

Call (248) 538-5283Schedule a tour
Call nowSchedule a tour